RBI likely to raise rates: Why inflation, crude and global rates matter
Story continues below.
Subscribe to see fewer ads.
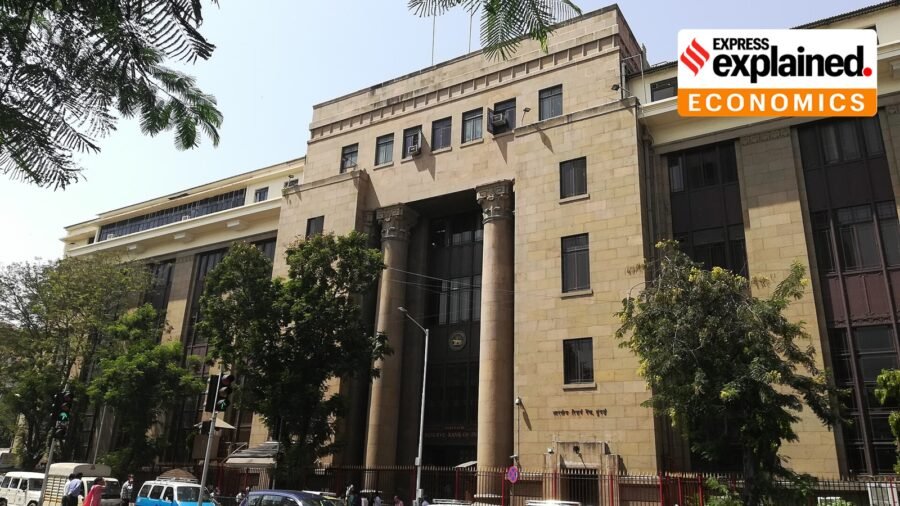
Why the RBI rate hike now?
The central bank’s August MPC minutes had already indicated such a move. Since then, incoming data on domestic inflation and growth, coupled with a global backdrop of higher US interest rates, bond yields and commodity prices, has left little room for the RBI to wait. The US Federal Reserve recently raised its policy rate by 25 bps to 3.75-4%. US benchmark yields have also risen sharply, by 49 bps to 5.27% and by 25 bps to 7.21% over the past month.
“After holding through 2026, the RBI faces growing pressure to raise rates at its October review, and a 25-basis point hike to 5.50% is now a real possibility, which would be the first increase since early 2023,” said Rajeev Sharan, Head of Research, Brickwork Ratings.
“In our baseline, the RBI hikes by 25 bps in each of October and December to a terminal rate of 5.75%, though there is some risk of a one-and-done hike,” Nomura Global Market Research said. “Market expectations are now converging on two themes: removal of liquidity and RBI rate hikes,” said Pranjul Bhandari, Chief India Economist, HSBC Global Investment Research.
There are also analysts who expect the RBI to hold rates. “The RBI may not move rates in October, but it may move the market’s expectations. The policy decision could remain unchanged even as the policy message becomes incrementally cautious,” said Sneha Pandey, Fund Manager, Fixed Income, Quantum AMC.
Inflation getting broad-based
Story continues below this ad
Domestically, retail inflation is showing signs of becoming more broad-based. Price pressures are being driven by elevated energy prices and a rise in food inflation, while the impact of El Niño-related disruptions is becoming increasingly visible. Maharashtra has declared drought in about 265 of the state’s 358 talukas, covering nearly 74% of the state. The Union Agriculture Minister has also flagged the possibility of drought in other states, including Karnataka, Telangana, Andhra Pradesh and Rajasthan.
Lower reservoir levels, weather-related disruptions and higher energy prices are adding to inflationary pressures. Reservoir levels across India are about 20% below last year’s levels, which could also affect the rabi crop. The possibility of El Niño conditions extending into 2027 remains a key monitorable.
Besides, global headwinds continue to weigh on the outlook. The conflict in West Asia and the Russia-Ukraine war have added to economic uncertainty, while crude oil prices have risen above $100 a barrel, raising concerns over imported inflation and the impact on the country’s external balance.
CareEdge Ratings projects retail inflation to peak at 6% in the third quarter and average around 5% in FY27. Weather-related risks and volatile energy prices remain the key risks, it said. Retail inflation which was at 4.82% in August, is expected to be around 5.5%. It could remain above 5% for nearly three quarters. With WPI/PPI inflation around 10%, elevated crude oil prices and the possibility of a strong El Niño, markets have begun pricing in the prospect of rate hikes.
Story continues below this ad
With inflation rising and gaining breadth, and global interest rates and yields remaining elevated, the backdrop has become risky for India to allow the interest-rate differential with the US to narrow further. “Food inflation is becoming increasingly broad-based and moving beyond typical perishable prices. The increase in wholesale inflation is slowly spilling over into farming and non-farming sectors, creating a large wedge between CPI and WPI inflation,” Bank of America Securities economists Rahul Bajoria and Smriti Mehra said.
What’s the impact of an RBI rate hike?
If the repo rate rises, lending and deposit rates are expected to increase in near term. Loans linked to external benchmarks — particularly those directly linked to the repo rate — will see the impact almost immediately. Borrowers with such loans could see their equated monthly instalments (EMIs) rise, increasing their repayment burden.
Interest rates on loans linked to the marginal cost of funds-based lending rate (MCLR) are also likely to rise. Banks have the flexibility to revise MCLR-based lending rates depending on their funding costs, liquidity conditions and deposit mobilisation.
On the deposit side, rates are also expected to rise marginally. However, a sharper or sustained increase would depend on changes in liquidity and funding conditions that prompt banks to reassess deposit pricing.
Story continues below this ad
The RBI’s likely shift to a rate-hike cycle comes when the economy is facing a combination of rising inflationary pressures, elevated crude oil prices, tighter global financial conditions and strong domestic growth. The move would help contain demand and inflation expectations, but could also weigh on consumption and investment if borrowing costs remain elevated for an extended period.
Will the growth forecast be revised?
The Indian economy remained resilient in the first quarter of FY27, with GDP growth coming in at a better-than-expected 7.8% despite a challenging global environment. Consumption, investment and robust export growth supported the momentum, while high-frequency indicators such as GST collections, auto sales and bank credit remained healthy.
“Following the strong Q1 growth momentum, we now project FY27 growth at 7.3%,” CareEdge Ratings said. It expects the RBI to raise its GDP growth projection closer to its estimate, from the central bank’s previous forecast of 6.7%.
In the August review, MPC marginally raised its GDP growth forecast for FY27 to 6.7% from 6.6% and lowered its inflation projection to 5% from 5.1%, indicating that it expected price pressures to moderate over the course of the year despite near-term risks.
Story continues below this ad
The stronger-than-expected Q1 print, however, has changed the starting point for the full-year growth outlook. A higher-than-expected first-quarter performance means that even if growth moderates in the remaining quarters, the annual average could still come in above the RBI’s existing projection. This raises the possibility of an upward revision in the central bank’s growth forecast.
There are, however, risks to the outlook. Higher crude oil prices, elevated global interest rates, geopolitical tensions, trade-policy uncertainty and weather-related disruptions could weigh on growth in the coming quarters. Growth is likely to moderate in the second half of FY27.
Is it safe to reheat rice more than once?
By Sohail Khan · 4 Oct
China This Week | Rumours about Xi’s health, US jets arrive in Taiwan, and more
By Sohail Khan · 4 Oct
‘No filter’: Tamannaah Bhatia’s advice for dealing with bad skin days
By Sohail Khan · 4 Oct
Leave a Reply