How government has paved way for fee on UPI merchant payments above Rs 2,000
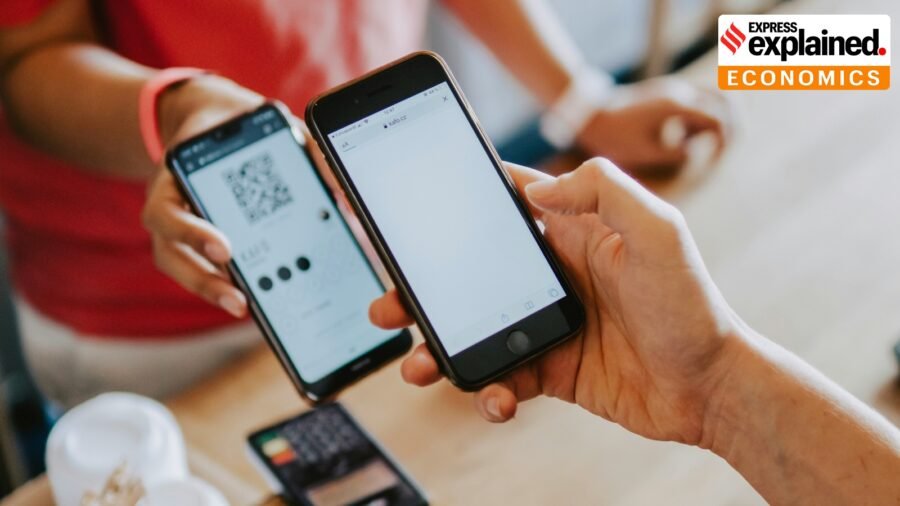
The government has barred banks and payment system providers from charging any fee on UPI transactions up to Rs 2,000, while leaving payments above that threshold outside the exemption.
The notification, therefore, creates the legal room for introducing charges such as the Merchant Discount Rate (MDR) on UPI payments above Rs 2,000.
MDR is a fee charged to merchants. So how will the consumer be affected? And, why is the government looking to bring in such a fee? We explain
What is MDR?
Story continues below.
Subscribe to see fewer ads.
MDR is a fee charged to merchants for processing digital payments, and is typically shared among banks and other entities involved in processing the transaction. Credit cards, for instance, face an MDR of 1-3% of transaction value while it is up to 0.9% for debit cards.
UPI, unlike card payments, has operated under a zero-MDR regime since January 2020. To be clear, such a fee would not apply on person-to-person payments — that is, if you transferred an amount more than Rs 2,000 to a friend.
Why does this matter?
Two reasons. First, because it is the consumer who could end up facing the fee. In the case of credit cards, for instance, merchants often pass on the MDR amount to the consumers. The same may happen with UPI.
Second, such a fee would affect a significant chunk of UPI transactions. While transactions above Rs 2,000 accounted for only 4% of person-to-merchant (P2M) UPI payments by volume in 2025-26, these made up around two-thirds of UPI payments by value. In 2025-26, more than 24,000 crore UPI transactions worth Rs 314 lakh crore were made.
Story continues below this ad
Would a fee on large UPI payments change how people make payments? A sizable chunk would, it seems, if it led to merchants passing on any MDR on UPI transactions to them.
According to a LocalCircles poll of more than 20,000 people, if a fee is levied on UPI payments of more than Rs 3,000 at large merchants, only 12% said they would continue using UPI. This percentage fell further to 2% when asked what they would do if merchants were to recover any transaction fee from customers for UPI payments of more than Rs 3,000.
What the government is planning
The government has already indicated that this is the direction in which the framework could move. In August, after Parliament amended the Payment and Settlement Systems Act, the Finance Ministry said that if MDR is introduced on UPI, it would only apply to a “limited set” of merchant transactions above a specified threshold and at a nominal rate.
In a statement last month, the ministry had clarified that consumers would not be charged and all person-to-person, or P2P, UPI transactions would continue to remain free.
Story continues below this ad
At the moment, these specifics are not clear, and while there are currently no MDR charges on UPI transactions, according to reports, an MDR of around 0.4% may be levied on high-value person-to-merchant UPI payments.
The fresh notification comes after the Taxation and Other Laws (Amendment) Bill, 2026, which was passed by Parliament last month, amended Section 10A of the Payment and Settlement Systems Act, 2007 to remove the exemption from any bank charges to electronic payments under section 269SU of the Income-tax Act. Section 269SU applied to every person having a business turnover of over Rs 50 crore.
Section 10A of the Payment and Settlement Systems Act, 2007 said no bank or system provider can impose any charge on payments made through electronic modes prescribed under Section 269SU. These modes were RuPay debit cards, BHIM-UPI, and UPI-QR code. As such, the amendment had paved the way for a MDR fee to be imposed on UPI and RuPay debit card payments to large merchants such as Amazon and Flipkart.
Why the need for charges on UPI
More than 55 crore people use UPI now and 703 entities — from banks to payment service providers — are involved in facilitating its transactions.
Story continues below this ad
But there are costs involved in maintaining the digital payments infrastructure, and these have been borne by banks and payment service providers for years. This may be as high as Rs 20,000 crore every year.
The Standing Committee on Finance noted in a report in March that the “absence of MDR makes the UPI ecosystem financially unsustainable”.
The government has cited three key reasons for moving towards charges on certain UPI transactions:
- Growth of UPI: “With exponential transaction volumes, the system requires significant and continuous upgrades in cybersecurity, fraud prevention, and infrastructure,” the Ministry of Finance earlier said.
- Market expansion: “It is necessary to increase competition by encouraging more companies to expand their operations, which requires a self-sustaining revenue model,” it said.
- Self-sustainability: “Reliance on subsidies alone is not viable for the next wave of growth. A balanced framework is required to ensure that UPI remains robust, inclusive, and future-ready,” it added.
had earlier reported that companies operating UPI platforms had told the government in private meetings that the cost of securing the payments network is rising sharply, with emerging artificial intelligence (AI) systems adding a new layer of risk to fraud prevention and cybersecurity.
Story continues below this ad
Industry insiders had previously estimated that the total spends on security-related inputs account for over 20% of the total costs of running a UPI platform annually, which could rise sharply in deploying cutting-edge security software to prevent risks posed by AI systems like Anthropic’s Mythos.
How Panna brought its vultures back from a 99% population crash
By Sohail Khan · 15 Sep
Why Saudi Arabia engages with BRICS without formally joining it
By Sohail Khan · 15 Sep
The government’s 7.8 per cent growth number may be accurate. Why doesn’t it feel right?
By Sohail Khan · 15 Sep
Leave a Reply