Will govt increase small savings scheme rates?
Synopsis
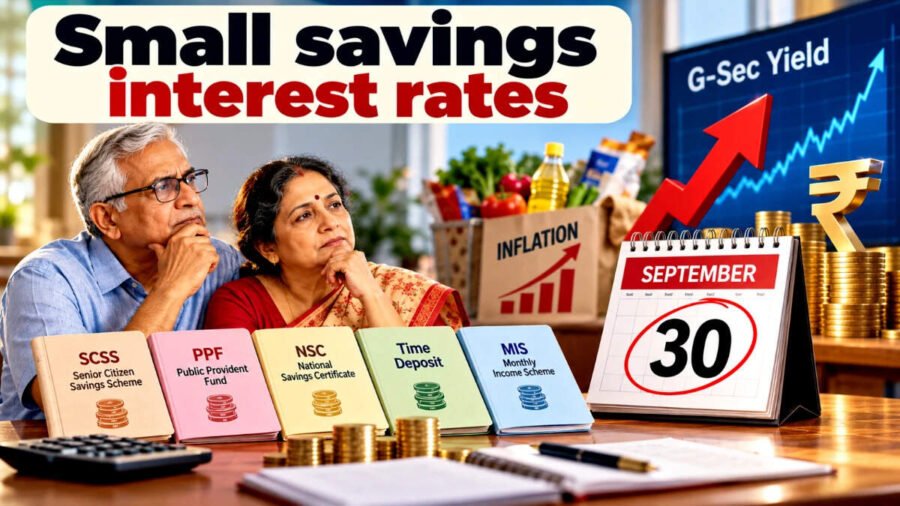
On September 30, 2026, the Finance Ministry will evaluate interest rates for small savings schemes. With high inflation and increasing G-Sec bond yields, many are speculating about potential rate hikes. Currently, various schemes offer competitive returns exceeding 7%. Despite indicators suggesting adjustments, the government has kept rates steady for several quarters. The upcoming review will clarify the government's stance on these interest rates.
Inflation is shooting up and the Government Bond yield is also high. Will this lead to an interest rate hike on small savings schemes, which are due for quarterly review by the Finance Ministry on Wednesday, September 30, 2026?
Small savings interest rates that the ministry will review on Wednesday will be applicable for the October-December 2026 quarter. If the ministry increases the rates, it will be the first rate change since December 2024, when rates for Sukanya Samriddhi Account (SSA) and the 3-year time deposit scheme were increased.
Inflation is high, and the G-Sec bond yield is also up; however, that doesn’t necessarily mean that the government may increase small savings scheme interest rates. Despite the yield of government bonds rising, they are yet not close to the rates offered by small savings schemes. Many of the small savings schemes have already been offering over 7% interest rates, with the Senior Citizen Savings Scheme (SCSS) and the SSA offering 8.2% each. Previously, on many occasions, the government didn’t decrease the rates despite many indicators suggesting so. Since it has been giving relaxation to small savings scheme investors for a long time, the big question is: can the government increase the rates this time?
Let’s first see how inflation and the G-Sec bond yield may influence small savings interest rates.
Role of inflation in small savings scheme interest rates
The government ensures that the real return that investors get remains attractive. So, if inflation is high, small savings schemes’ rates can be kept slightly higher and vice versa. When inflation rises, the Reserve Bank of India (RBI) often goes for a policy rate increase to manage inflation; this raises overall interest rates in the economy, and this also raises G-Sec interest rates. The high G-Sec rate can put competitive pressure on small savings rates.
If we look at Consumer Price Index (CPI) inflation data for the last few months, inflation rose from 3.48% in April 2026 to 4.82% in August. However, it is still far from the RBI’s upper band limit of 6%, but some inflationary pressures can be felt at 4.82%. Not just that, inflation is expected to rise further in the next few months. It may compel the government to consider increasing small savings rates.
G-Sec bond yield is high
How high G-Sec bond yields put pressure on the government to increase small savings scheme rates can be understood by a market-linked formula recommended by the Shyamala Gopinath Committee in 2014.
According to the formula, small savings scheme rates are benchmarked to the average yields on Government Securities (G-Secs) of similar maturity periods from the previous quarter with a positive spread (usually 25–100 basis points) added to make them look more attractive for investors.
Take the example of the PPF interest rate, which is 7.1% per annum. The near-3-month average of the 10-year G-Sec yield (from June 1, 2026, to September 27, 2025) is 6.870%, according to Investing.com. If we add 25 basis points to it, the rate rises to 7.12%, which is higher than the interest rate of the PPF. It means the government can increase the interest rate of the PPF if it wants.
Aakanksha Shukla, AVP, wealth management, Master Capital Services Limited, told ET Wealth Online that for the October quarter that bond yields have hardened over the July-September period, with the 10-year yield rising above 7%.
“August inflation at 4.82% points the same way. On the long end, the formula has broadly caught up with what the PPF already pays, while the SCSS still sits above its formula value. The signal is mixed, not one-directional,” says Aakanksha.
Adhil Shetty, CEO, Bankbazaar, says that small savings rates are broadly linked to government bond yields of similar maturities, with a prescribed spread for different schemes.
Shetty says, “These yields are therefore an important reference when rates are reviewed. G-sec yields have moved higher in recent months, which could support higher rates under the existing framework. The broader interest rate environment also matters when assessing rates for different schemes.”
However, the Shyamala Gopinath Committee formula is a recommendation, and the Finance Ministry is not bound by it. The government has overlooked the formula many times to keep the rates high.
Aakanksha said, “Rates have held steady for nine straight quarters, with the last actual revision back in the January to March 2024 quarter. Small savings collections are also running strong, up roughly 41% year-on-year in the first quarter of this fiscal, so there is no funding pressure forcing a move.”
Why the government may not increase small savings interest rates
Have a look at small savings scheme interest rates for the July-September quarter.
| Instruments | Rate of Interest w.e.f 01.01.2026 to 31.03.2026 | Compounding Frequency |
| Post Office Savings Account | 4.00% | Annually |
| 1 Year Time Deposit | 6.9% (Annual Interest ₹708 for ₹10,000/-) | Quarterly |
| 2 Year Time Deposit | 7.0% (Annual Interest ₹719 for ₹10,000/-) | Quarterly |
| 3 Year Time Deposit | 7.1% (Annual Interest ₹729 for ₹10,000/-) | Quarterly |
| 5 Year Time Deposit | 7.5% (Annual Interest ₹771 for ₹10,000/-) | Quarterly |
| 5 Year Recurring Deposit Scheme | 6.70% | Quarterly |
| Senior Citizen Savings Scheme | 8.2% (Quarterly Interest ₹205 for ₹10,000/-) | Quarterly and Paid |
| Monthly Income Account | 7.4% (Monthly Interest ₹62 for ₹10,000/-) | Monthly and paid |
| National Savings Certificate (VIII Issue) | 7.7% (Maturity Value ₹14,490 for ₹10,000/-) | Annually |
| Public Provident Fund Scheme | 7.10% | Annually |
Source: India Post website
You can see that the savings account rate is 4%, while all other schemes are providing rates of 6.7% and higher. These are some of the best rates provided by low-risk, stable-return investments, including public sector bank savings accounts and fixed deposits (FDs). The government, therefore, may not feel the pressure to increase the small savings rates anytime soon.
However, it will be known only after the quarterly review on Wednesday.
(Join our ETWealth WhatsApp channel for all the latest updates)
Add 

(Catch all the Personal Finance News, Breaking News, Budget 2025 Events and Latest News Updates on The .)
…more
Anthropic’s IPO could value AI giant above $2 trn
By Sohail Khan · 29 Sep
Nothing Headphone 1 Pro launched: Price, specs
By Sohail Khan · 29 Sep
Trump’s govt-funded ads face bipartisan backlash
By Sohail Khan · 29 Sep
Leave a Reply