Insurance mis-selling is arising: Ajay Seth
Benchmarks
Nifty23,140.5077.41
FEATURED FUNDS★★★★★
Motilal Oswal Midcap Fund Direct-Growth
5Y Return
20.4 %
Invest Now
Enter search text:
Business News›Industry›Banking/Finance›Insure›Insurance mis-selling is arising because upfront commissions are too high: Ajay Seth, Chairman, IRDAI
Read Today's Paper
Insurance mis-selling is arising because upfront commissions are too high: Ajay Seth, Chairman, IRDAI
Synopsis
The benefit of cost efficiency should be passed on to customers. This entire exercise is intended to ensure that the public and policyholders benefit. For a life insurance savings product, the outcome should be better returns. In general insurance, it should result in better claim ratios. Cost efficiencies should get passed on through lower premiums, or the rate of increase in premiums should be moderated, or returns on savings products should be better than they are today, says Ajay Seth.
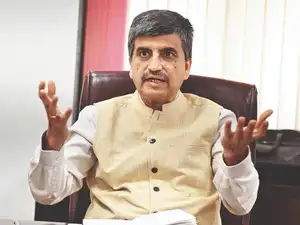
There is significant information asymmetry in the insurance sector. It should not be allowed to remain
Ajay Seth, chairman of the Insurance Regulatory and Development Authority of India (Irdai), discusses with ET the mounting concerns over mis-selling and cost efficiencies, explaining the broad central theme that prompted the regulator to issue its consultation paper on proposed sectoral reforms that will likely take effect next year. Edited excerpts:
What is the principal objective of the consultation paper?
The intent is, first, to expand coverage; second, to improve affordability; third, to enhance accessibility; and fourth, to tackle compulsory bundling and reduce mis-selling.
If I have to identify one goal, it is to enhance value to policyholders. By doing so, trust in insurance will grow and so will be uptake, making distribution relatively easier, expanding coverage and ultimately improving the economics of insurance. It will build stronger insurers and distributors aligned to policyholder expectations.
Do you believe insurers will pass the savings from lower commissions on to customers, or could they retain the benefit?
The expectation is very clear: the benefit of cost efficiency should be passed on to customers. This entire exercise is intended to ensure that the public and policyholders benefit. For a life insurance savings product, the outcome should be better returns. In general insurance, it should result in better claim ratios. Cost efficiencies should get passed on through lower premiums, or the rate of increase in premiums should be moderated, or returns on savings products should be better than they are today.
Once higher commissions no longer determine insurer access to distribution networks, they will differentiate themselves and compete on price, products and service quality.
(You can now subscribe to our WhatsApp channel)
(Catch all the Business News, Breaking News and Latest News Updates on The .)
…moreless
(You can now subscribe to our WhatsApp channel)
Read More News on
Ajay SethIRDAIinsurance industrypolicyholders
(Catch all the Business News, Breaking News and Latest News Updates on The .)
…moreless
Enter search text:
Stories you might be interested in
Burnham hints at new taxes in UK for social reform
By Sohail Khan · 28 Sep
Armani open to more investors for 15% stake
By Sohail Khan · 28 Sep
Time is on India’s side: Baume & Mercier CEO
By Sohail Khan · 28 Sep
Leave a Reply