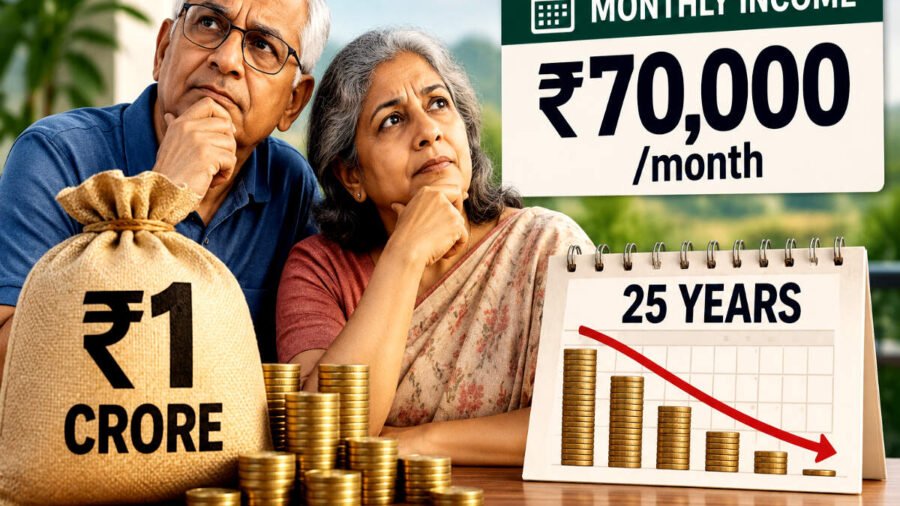
Can you get Rs 70K/m for 25 years from Rs 1cr corpus?
Synopsis
A retirement fund of Rs 1 crore can serve as a vital asset, but navigating withdrawal rates is imperative for longevity. Financial advisors advocate for conservative investments that yield stable returns, as excessive withdrawals may accelerate depletion of the corpus. A monthly draw between Rs 30,000 and Rs 58,333 can help maintain fiscal health, with inflation as a key consideration.
Rs 1 crore is quite a large amount for many Indians, and it may be the corpus size you may want to retire with. But can it give you a lifelong income? The answer lies in your monthly income expectation from the Rs 1 crore corpus. Do you want to withdraw Rs 30,000, Rs 50,000 or a higher amount from the corpus? Do you want to withdraw at a fixed or an increasing rate? A high-amount withdrawal may lead to an early erosion of the corpus. But if you choose a low withdrawal amount, it may not be sufficient to cover your expenses. So, what’s the right amount that helps you withdraw monthly expenses from a Rs 1 crore retirement corpus for at least 25 years?
Monthly income from Rs 1 crore corpus at different withdrawal rates
You can set any withdrawal rate, but if you want your corpus to last longer, it should be lower than the rate of return you get from the corpus. But when it comes to a retirement corpus, you can’t just chase high returns. The corpus should be invested in a low-risk instrument from which you can get stable returns in the long run.
| Annual return | withdrawal rate | Annual withdrawal | Monthly withdrawal | year corpus will end |
| 6% | 4% | ₹ 4,00,000 | ₹ 33,333 | Lifetime |
| 6% | 5% | ₹ 5,00,000 | ₹ 41,667 | Lifetime |
| 6% | 6% | ₹ 6,00,000 | ₹ 50,000 | 49 years |
| 6% | 7% | ₹ 7,00,000 | ₹ 58,333 | 28 years |
| 6% | 8% | ₹ 8,00,000 | ₹ 66,667 | 21 years |
In the calculations, you can see that at a 6% annualised return and at 4%-7% withdrawal rates, the corpus will last more than 25 years. But the maximum amount you can withdraw in a month at those rates will be approximately Rs 58,333.
Also Read: 8th Pay Commission: AIDEF demands Rs 69,000 minimum pay, 3.83 fitment factor and 11-year pension commutation period
If you opt for a higher withdrawal rate of 8%, you can withdraw a monthly amount of Rs 66,667, but the corpus will last just 21 years.
Today, Rs 58,333 per month income may be sufficient for you, but its value may be much lower 20 years later. At a 5% inflation rate, the value of Rs 58,333 will be equal to Rs 21,985. Can you sustain on that monthly income 20 years from now?
What’s an alternative way to withdraw monthly income from Rs 1 crore corpus then?
To counter that effect, you may choose a method where you increase your withdrawal rate every year at the rate of inflation. If you take 5% as the long-term inflation rate and expect a 6% annualised return from your Rs 1 crore corpus, let’s see how long it will last.
| Year 1 monthly withdrawal | Increase in withdrawal rate/year | Return from corpus | How long corpus will last |
| ₹ 30,000 | 5% | 6% | 33 years |
| ₹ 35,000 | 5% | 6% | 27 years |
| ₹ 40,000 | 5% | 6% | 24 years |
| ₹ 45,000 | 5% | 6% | 21 years |
| ₹ 50,000 | 5% | 6% | 19 years |
In the table, you can see that if your monthly expense is Rs 30,000 or Rs 35,000 in today’s terms, a Rs 1 crore corpus can last more than 25 years. But if expenses are Rs 40,000 or higher, the Rs 1 crore corpus will be insufficient for 25 years.
Also Read: 8th Pay Commission calculator: Can Level 8 employees get Rs 18 lakh in arrears for report implementation delay?
Will Rs 30,000 or Rs 40,000 monthly expenses be sufficient for you?
Calculations suggest that a Rs 1 crore retirement corpus is sufficient only when your monthly expenses are low today and will remain the same when you retire. But if you have high monthly expenses and expect the same when you retire, you need a higher retirement corpus to begin with.
Bucket strategy is another way to invest Rs 1 crore corpus
You may also follow a bucket strategy if you want higher returns. In the bucket strategy, you allocate corpus to different buckets based on your immediate, medium and long-term requirements.
For the immediate needs, you can invest in liquid funds or a savings account where returns may be low but are stable. For the amount that you need in 2-3 years, you can invest in debt funds, where returns may be slightly higher than liquid funds. You may invest in equity savings funds for the amount required in 4 to 5 years. The money you need in 6-7 years will go to aggressive hybrid funds. The largest allocation will be in equity funds that will remain untouched for seven years.
The equity fund allocation will be used for the next seven-year cycle, and the cycles will go on.
The bottom line is that if you keep your withdrawal rate low, your money can last a lifetime, but if you want a high withdrawal rate, it’s better to start with a higher corpus amount than Rs 1 crore.
(Join our ETWealth WhatsApp channel for all the latest updates)
Add 

(Catch all the Personal Finance News, Breaking News, Budget 2025 Events and Latest News Updates on The .)
…more
FDI equity inflows rise 6% to $20 billion in Q1; US contribution drops, Japan tops
By Sohail Khan · 26 Sep
Forex reserves drop to $781 billion after hitting a peak of $785 billion
By Sohail Khan · 26 Sep
Ownly launches in H’bad, bets on profitability
By Sohail Khan · 26 Sep
Leave a Reply